GST Council’s 57th Meeting: Key Recommendations and ITC Concerns Under Section 16(2)(c)
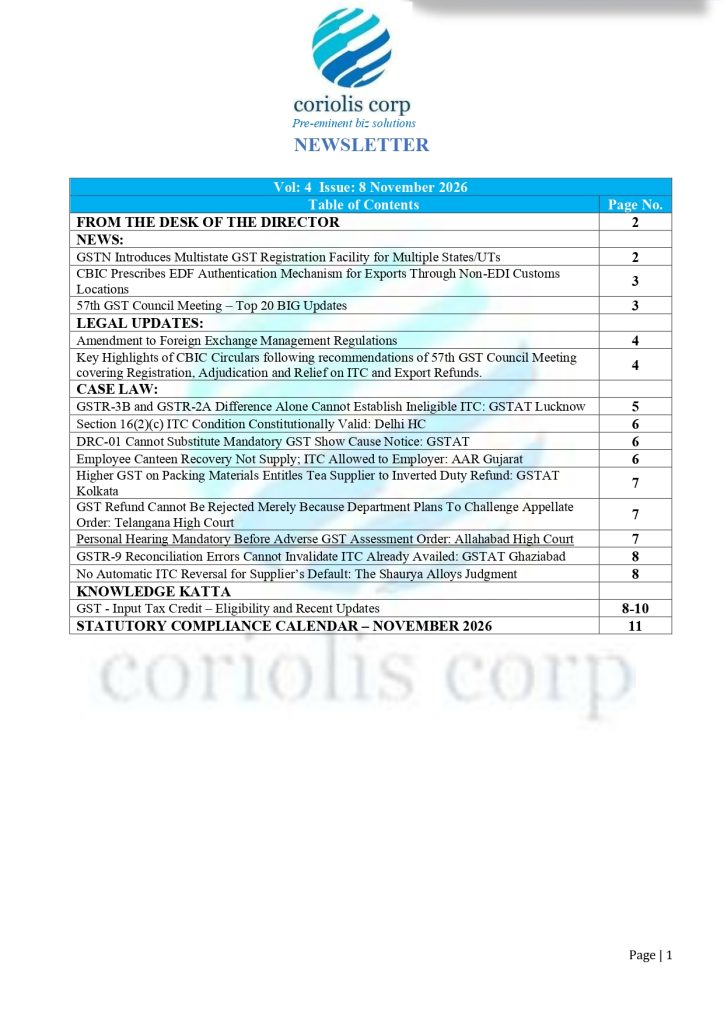
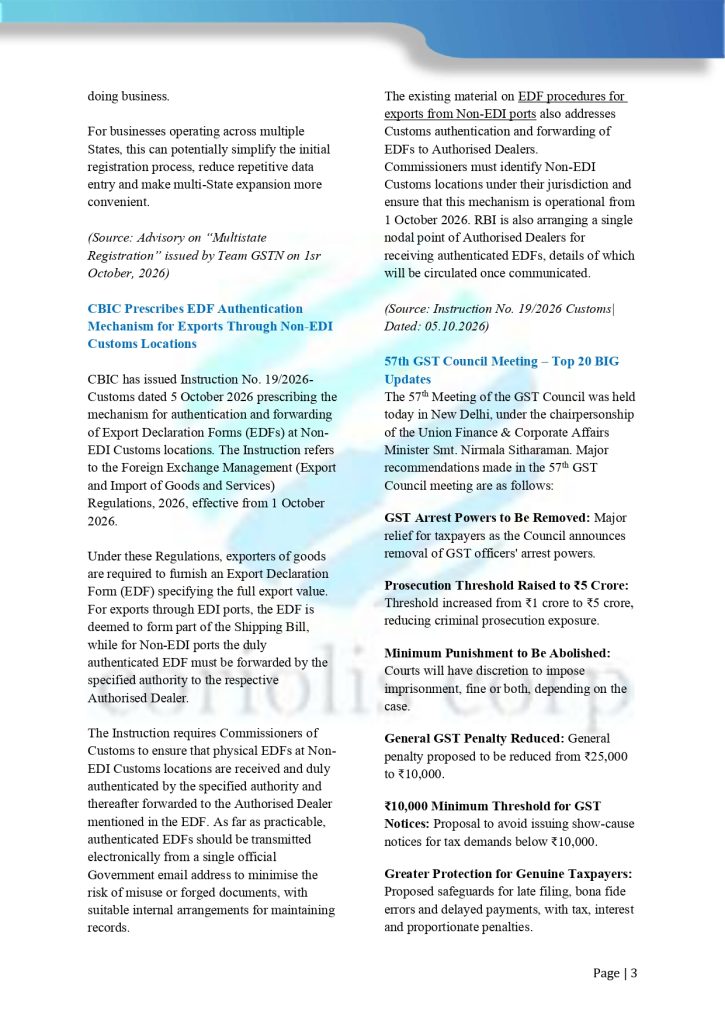
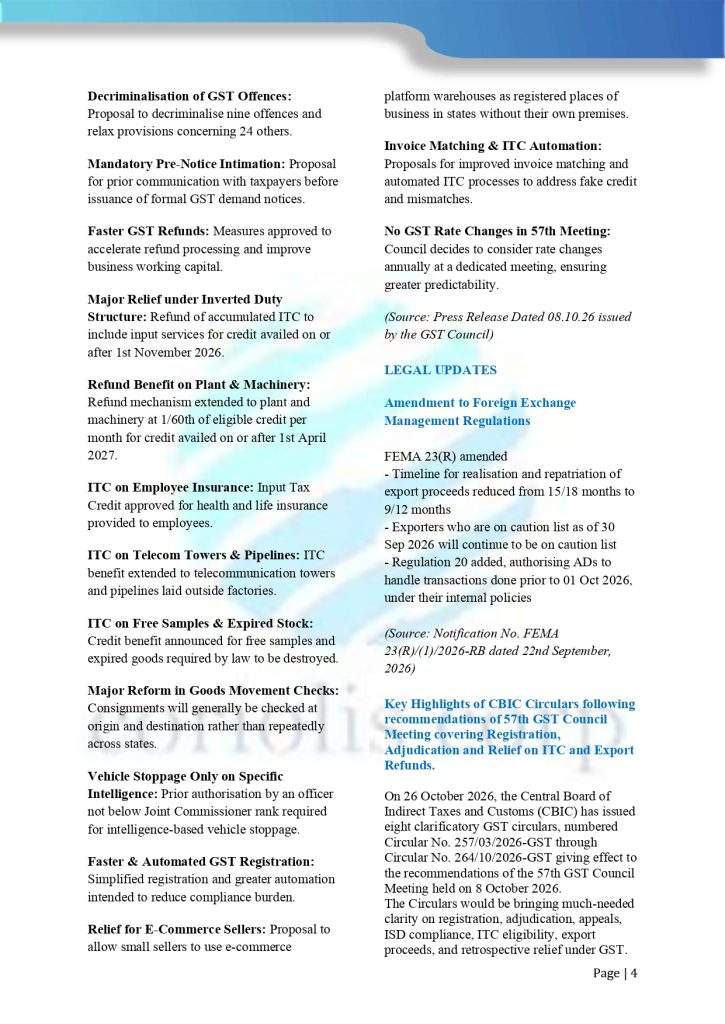
The 57th GST Council meeting made several recommendations relating to GST process reforms, primarily covering registration, returns, refunds and adjudication. The Council also recommended clarifications on the applicability of GST to certain goods and services, along with measures aimed at facilitating trade and streamlining GST compliance.
The major recommendations of the 57th GST Council meeting are covered in the News Section of this newsletter.
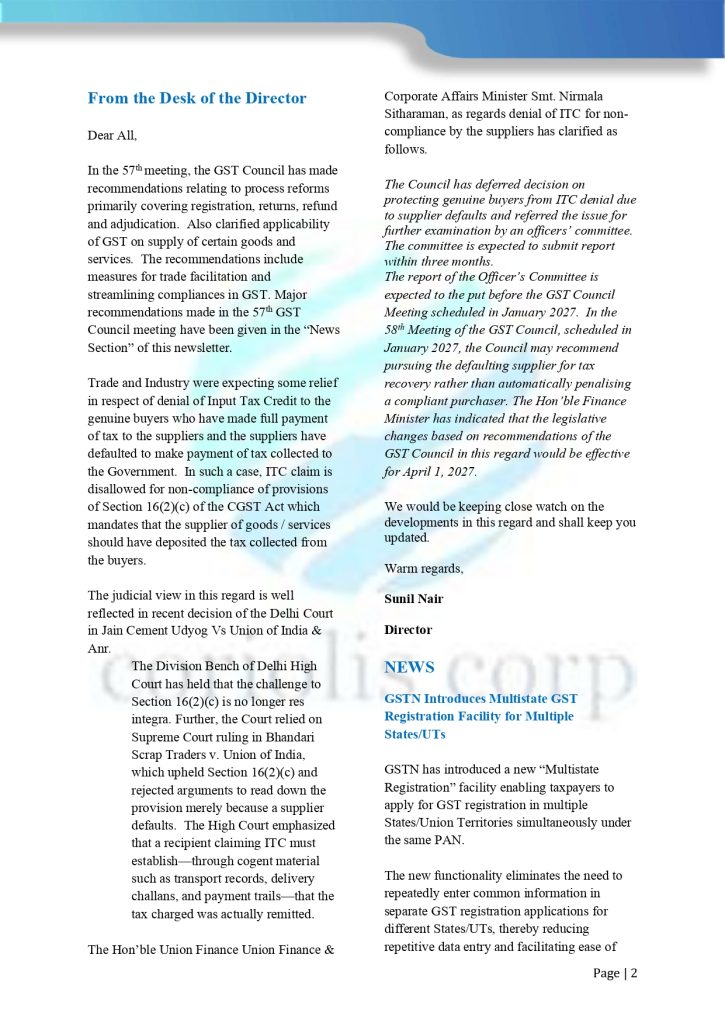
Input Tax Credit Denial to Genuine Buyers Under GST
Trade and industry were expecting relief regarding the denial of Input Tax Credit (ITC) to genuine buyers who have made full payment of the tax charged by their suppliers, but whose suppliers have subsequently defaulted in depositing the tax collected with the Government.
Under Section 16(2)(c) of the Central Goods and Services Tax (CGST) Act, 2017, one of the conditions for claiming ITC is that the tax charged in respect of the supply must have been actually paid to the Government, either in cash or through utilisation of input tax credit.
Accordingly, where a supplier of goods or services fails to deposit the GST collected from the recipient with the Government, the recipient’s ITC claim may be disallowed for non-fulfilment of the condition prescribed under Section 16(2)(c) of the CGST Act.
This issue has been a significant concern for businesses, particularly genuine buyers who have fulfilled their contractual payment obligations but may face ITC denial due to the supplier’s default.
Judicial Developments on ITC Denial Due to Supplier Default
The judicial position concerning the denial of ITC to genuine buyers is reflected in recent decisions, including the decision of the Delhi High Court in Jain.
The issue continues to be relevant for businesses claiming GST Input Tax Credit, as the statutory condition under Section 16(2)(c) concerns actual payment of tax to the Government by the supplier.
The applicable judicial principles and their implications for taxpayers should be considered in the context of the specific facts and circumstances of each case.
Read More About: Direct Tax Service